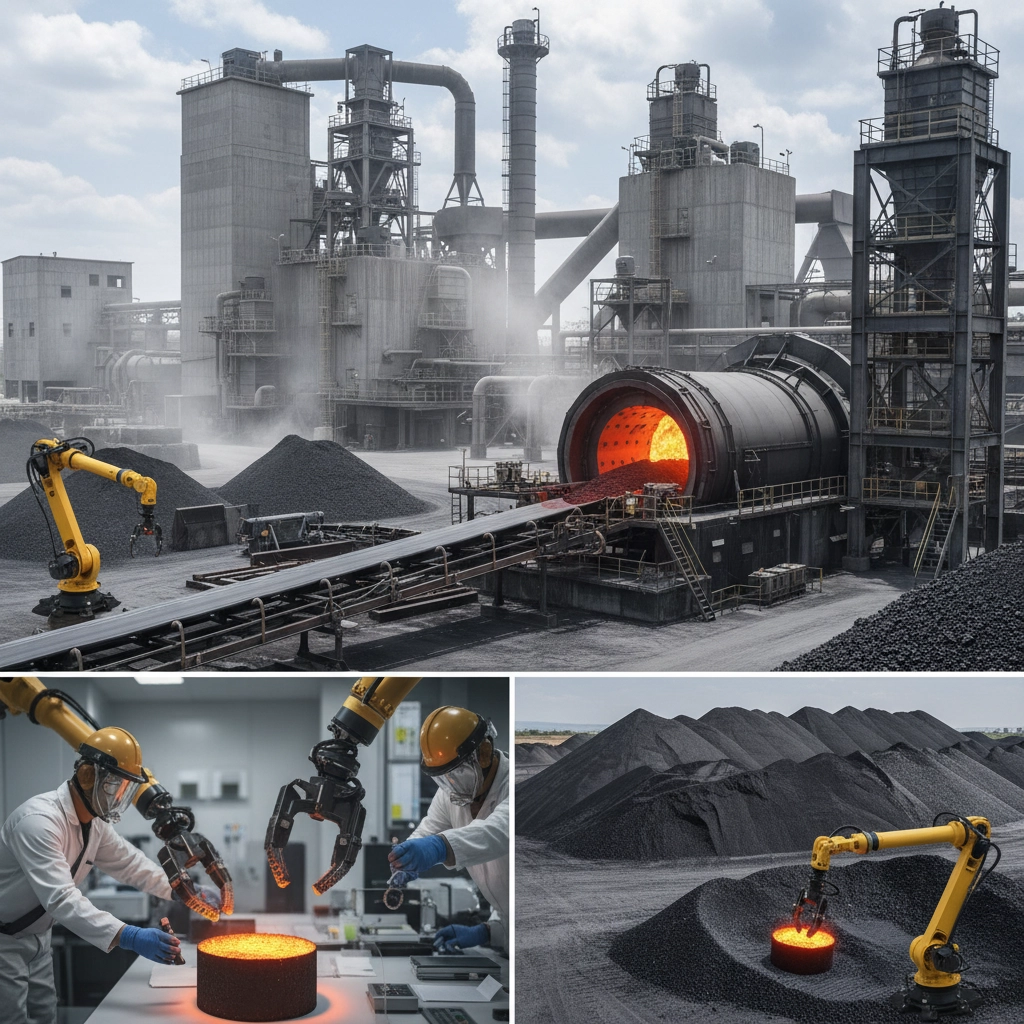


Procuring raw materials for carbon production often begins with a critical query regarding the petcoke price per ton, as this variable directly dictates the operational margins of graphite electrode and anode manufacturing. Petroleum coke, a byproduct of the oil refining process, serves as the foundational carbon source for a vast array of industrial applications, from aluminum smelting to the production of high-density graphite blocks.
Understanding the pricing dynamics of petcoke requires more than a simple glance at a ticker; it involves analyzing the interplay between refinery output, global energy demands, and the specific grade of coke—whether green or calcined—required for the end product. For manufacturers in the non-metallic mineral products sector, price volatility can disrupt long-term project planning and supply chain stability.
This analysis explores the cost drivers affecting petroleum coke, how these prices ripple through the production of downstream graphite products, and the strategic considerations procurement officers must employ to mitigate financial risk in an unstable commodity market.

Analyzing the Market Drivers of Petroleum Coke Pricing

The fluctuation of petcoke pricing is rarely an isolated event; it is deeply entwined with the global crude oil refining capacity and the demand for low-sulfur fuels. When refineries increase their throughput to meet gasoline and diesel demands, the volume of petroleum coke produced as a residue increases, which typically exerts downward pressure on the price per ton.
However, the market is segmented by sulfur content. High-sulfur petcoke is often utilized in cement kilns and power plants, where pricing is lower due to environmental constraints. Conversely, low-sulfur or needle coke is essential for the graphite industry, commanding a significant premium because of its ability to form a highly ordered crystalline structure during graphitization.
Logistical costs also play a pivotal role. Since petroleum coke is a bulk commodity, the distance from the refinery to the calciner or the final manufacturing plant—such as those specializing in graphite electrodes or powder—can add substantial premiums to the landed cost per ton.
Technical Distinctions Between Green and Calcined Coke Costs
For a procurement manager, the distinction between "green" coke and "calcined" coke is the most critical factor in calculating total expenditure. Green coke is the raw material as it leaves the delayed coker unit; it contains volatile organic compounds that must be removed before it can be used in high-temperature applications.
Calcination is the process of heating green coke to temperatures exceeding 1,300°C to drive off volatiles and shrink the pores. This process adds a significant "value-add" cost to the price per ton, involving high energy consumption and specialized equipment like pot-type calciners. Therefore, the price of calcined coke reflects both the raw material cost and the operational cost of thermal processing.
Choosing between purchasing green coke and investing in in-house calcination—as seen in integrated facilities with annual capacities for calcined coke—depends on the scale of production and the desired level of quality control over the final carbon density and purity.
Industrial Applications and Their Sensitivity to Carbon Costs
The impact of carbon pricing varies significantly across different industrial sectors. In the metallurgy sector, petroleum coke is utilized as a carburizing agent to increase the carbon content of steel. Here, the price sensitivity is high, and buyers often shift between different grades of carbon additives to maintain cost-efficiency.
In the production of graphite electrodes and rods, the requirement is for ultra-high purity and specific morphology. The cost of the needle coke precursor is a dominant component of the final product's price. Any spike in the needle coke price per ton directly affects the competitiveness of graphite electrodes used in electric arc furnaces (EAF), which are critical for modern green steel production.
Furthermore, specialized products like graphite crucibles, tubes, and plates rely on high-density graphite powders. The precision and refractoriness (often > 2000°C) of these materials require high-grade coke, meaning that the "economy" grades of petcoke are irrelevant; only the premium, low-ash grades impact the cost structure of these precision components.
Measuring the Impact of Raw Material Volatility on ROI
To evaluate the Return on Investment (ROI) for carbon-based manufacturing, firms must model the correlation between feedstock costs and final product margins. When the price per ton of petcoke rises, the cost of goods sold (COGS) increases, which can either compress margins or force a price increase for the end customer.
The following data illustrates the relative cost efficiency when shifting from generic carbon sources to optimized, high-density graphite precursors, focusing on the reduction of waste and improvement in thermal conductivity.
petcoke price per ton Performance Metrics
As demonstrated, while high-grade precursors may have a higher initial price per ton, their efficiency in the graphitization process leads to higher bulk density (1.68-1.85 G/cm3) and lower ash content (0.05%), ultimately reducing the cost per unit of finished graphite product.
Strategic Procurement Frameworks for Industrial Carbon Materials
Effective procurement in the carbon sector requires a shift from spot-market buying to strategic sourcing. Relying solely on the current spot petcoke price per ton exposes a manufacturer to extreme volatility and potential supply shortages during refinery maintenance cycles.
Diversification is key. By sourcing from multiple regions—such as North America, Southeast Asia, and Eastern Europe—companies can hedge against regional policy changes or logistical bottlenecks. Furthermore, maintaining a safety stock of calcined coke can protect production schedules when green coke prices spike.
Technical auditing of suppliers is equally important. A lower price per ton is a liability if the material has high ash content or inconsistent particle size, as this leads to structural defects in graphite electrodes or increased failure rates in graphite crucibles.
Future Outlook on Carbon Feedstock and Sustainability Shifts
The petroleum coke market is likely to face increasing pressure from environmental regulations targeting sulfur emissions and carbon footprints. As industries move toward "Green Steel" and decarbonization, the demand for ultra-high power graphite electrodes will continue to grow, but the sourcing of the carbon will need to evolve.
We may see a shift toward synthetic graphite or bio-based carbon precursors to reduce reliance on refinery byproducts. However, for the foreseeable future, petcoke remains the most viable economic feedstock due to its established supply chain and the high efficiency of current graphitization technologies.
Innovations in calcination technology, such as the implementation of automatic feed proportioning systems and more energy-efficient furnaces, are expected to decouple the final product cost from the raw petcoke price per ton by reducing operational overhead.
Comparative Evaluation of Carbon Feedstock Selection Criteria
When selecting a carbon source, the decision must be based on a multi-dimensional matrix rather than price alone. The following table compares different carbon feedstocks used in the manufacture of graphite products to assist in procurement decision-making.
Each material grade presents a trade-off between the initial cost per ton and the resulting technical performance of the finished graphite component.
| Feedstock Type | Primary Use Case | Cost Impact | Key Technical Metric |
|---|---|---|---|
| High-Sulfur Petcoke | Cement & Power | Low Cost | High Ash Content |
| Low-Sulfur Petcoke | General Carbon | Moderate Cost | Standard Purity |
| Needle Coke | Graphite Electrodes | High Premium | Anisotropic Structure |
| Calcined Petroleum Coke | Anode Production | Processing Added | Low Volatiles |
| Synthetic Graphite | High-End Electronics | Very High Cost | Ultra-High Purity |
| Carburizing Agent | Steel Smelting | Variable/Market | Fixed Carbon % |
For those requiring precision graphite components, such as graphite tubes or plates with high corrosion resistance, the investment in needle coke and professional calcination is non-negotiable for ensuring material integrity.
Frequently Asked Questions
Conclusion
The volatility of the petcoke price per ton is an inherent challenge for the carbon and graphite industry. Success in this sector requires a sophisticated approach to procurement that balances the raw commodity cost with the technical requirements of the final application. By focusing on material purity, optimizing the calcination process, and diversifying supply chains, manufacturers can maintain stable margins despite market fluctuations.
Readers evaluating carbon feedstock and high-performance graphite solutions can review the relevant product and company information available through www.nlgraphite.com to ensure their specifications meet industrial standards for refractoriness and conductivity.